
Last updated: October 3, 2026
The short answer
- Who must have it: Super Visa holders need at least $100,000 in emergency medical coverage, valid one full year from the date of entry — and IEC/Working Holiday participants must be insured for their entire stay, or their work permit gets cut short to match the policy.
- What it costs without it: A single hospital night can run a non-resident ~$3,500–5,000, and an ICU day can top ~$10,000. Insurance isn’t a nice-to-have here; it’s the difference between a bad week and a five-figure bill.
- What to buy: At least $500,000–1 million in emergency medical coverage, repatriation included, a winter-sports rider if you’re skiing, and a policy that’s paid for before you fly — quotes don’t count.
I’ll be honest: travel insurance is the least fun part of planning a Canada trip, and it’s the one I’d fight you over. I’ve seen too many people budget every dollar for flights, hotels, and poutine, then treat insurance as an optional extra — and learn, in the sweatiest way possible, that Canadian hospitals are very good at medicine and very serious about billing. A non-resident hospital stay here can easily top $5,000 a day. (I checked the current Super Visa rules on IRCC’s official page while writing this — everything below reflects the 2026 requirements as published there.)
So here’s my planner-brain guide to getting this right: who legally needs coverage, what the numbers actually look like, what your policy must include, and the exclusions that trip people up. Do not skip this one — trust me on this one.
What Canadian healthcare actually costs a visitor
Here’s the thing about “free” Canadian healthcare: it’s free for residents who pay into the system through taxes. Visitors pay full freight, and the freight is eye-watering. I once paid out of pocket at a Vancouver walk-in clinic when my provincial card was being replaced — $175 for a ten-minute visit and a prescription. I got reimbursed later. A visitor would not.
These are typical published 2026 non-resident rates in Canada (marked ~ where they vary by province and hospital):
| Service | Typical cost for non-residents (CAD) |
|---|---|
| Walk-in clinic consultation | ~$150–300 |
| Emergency room visit (facility fee only) | ~$800–1,200 |
| Specialist consultation | ~$500+ |
| MRI or CT scan | ~$2,000 |
| Ambulance ride | ~$500–1,000 |
| Hospital ward, per night | ~$3,500–5,000 |
| Intensive care (ICU), per day | ~$10,000+ |
| Air ambulance / medical repatriation | ~$50,000+ |
And fair warning: the hospital bill and the doctor’s bill are often separate invoices in Canada, so your policy needs to cover “physician services,” not just the room. A simple broken leg on a Banff hiking trail can cascade into a $20,000+ episode once you add the ER, X-rays, surgery, and physio — ask me how I know that the Rockies are beautiful and expensive (okay, you know from the table). Planning a mountain trip? Read our Banff travel guide and our 2-day Banff itinerary with this chapter in mind.
Who legally has to have insurance in 2026
Most tourists aren’t legally required to buy insurance — but border officers can ask for proof you can support yourself financially, and a valid policy is the cleanest way to show it. Two groups don’t get a choice at all.
Super Visa holders: the exact 2026 rules
The Parent and Grandparent Super Visa lets family visit for up to five years per entry — and the insurance requirement is non-negotiable. I double-checked every item below on IRCC’s official Super Visa page before writing this, because getting one detail wrong can sink an application:
- Minimum $100,000 CAD in emergency medical coverage per person. Not $99,999. It’s the floor, not a suggestion.
- Valid for at least one full year (365 days) from the date of entry — even if the visit will be shorter. You need proof of this on each entry.
- Must cover health care, hospitalization, and repatriation.
- Must be issued by a Canadian insurance company, or a foreign insurer authorized by OSFI (the Office of the Superintendent of Financial Institutions) to provide accident and sickness insurance in Canada. That foreign-insurer option is new since January 2025 — before that, only Canadian companies counted.
- Must be paid in full, or in installments with a deposit paid. A quote is not proof of insurance. IRCC says this explicitly, and border officers can ask to review the policy on arrival.
Pro tip: renew before the policy expires if the stay continues — you must be able to show valid coverage on every entry, not just the first one. What does it cost? As a rough 2026 guide for $100,000 of Super Visa coverage: ages 40–54 pay ~$1,100–1,800/year, ages 55–64 ~$1,600–2,600, ages 65–69 ~$2,100–3,400, and ages 70–74 ~$2,900–4,800. Deductibles and pre-existing-condition coverage move those numbers a lot. → IRCC — Super Visa proof of health insurance (official)
IEC and Working Holiday: the full-stay rule
International Experience Canada (Working Holiday, Young Professionals, International Co-op) requires private health insurance covering your entire stay — medical care, hospitalization, and repatriation. Here’s the part people learn the hard way: if your insurance is shorter than your intended stay, the border officer will likely shorten your work permit to match your insurance end date — and you cannot extend it later. I’ve heard this called the most avoidable disaster in the IEC process, and I believe it.
Buy the insurance after you receive your Port of Entry letter of introduction (IRCC recommends this timing), make sure the policy explicitly says “repatriation,” and carry proof with you. Also on the arrival checklist: a passport valid for the whole stay, at least $2,500 CAD in funds, and a return ticket or the money to buy one. → IRCC — What type of insurance do I need for IEC? (official)
International students and digital nomads
Students usually get a basic health plan bundled with tuition, but it often has gaps — especially outside your province of study or for adventure sports. Many students top it up with private visitor coverage. Digital nomads are a trickier case: home-country plans almost never cover long stays abroad, and provincial plans (OHIP, MSP) aren’t available to you at all. A dedicated private policy is really the only safe option.
What your policy must actually cover
Don’t shop by price alone — a bargain policy with holes is just an expensive piece of paper. Here’s my checklist, in priority order:
- Emergency medical (the big one). Hospital stays, surgeries, ER visits. Aim for at least $500,000; $1 million is the industry standard for real peace of mind. Confirm it covers physician services separately from the hospital bill.
- Hospitalization details. Semi-private room, nursing care, X-rays, labs, oxygen. The unglamorous line items are where claims get denied.
- Repatriation and medical evacuation. An air ambulance home with a medical escort can top $50,000 — and this coverage also includes the return of remains in the worst case. IEC and Super Visa require the word “repatriation” explicitly.
- Emergency dental. Most solid 2026 policies include ~$300–500 for emergency dental pain relief — enough to get you through until you’re home.
- Trip interruption and delay. Canada is enormous and the weather does what it wants. A blizzard in Newfoundland or a wildfire in BC can end a trip overnight; this coverage recovers non-refundable bookings. Booking pricey tours? Ask about a “Cancel for Any Reason” (CFAR) upgrade.

That winter-highway photo above? That’s a trip-interruption claim waiting to happen — a single storm can close mountain passes for days, which is exactly why this coverage exists.
Exclusions: pre-existing conditions and high-risk activities
Knowing what your policy won’t cover matters as much as knowing what it will. Undisclosed conditions are the #1 reason claims get denied — and “I forgot” is not a defense.
The “stable” rule for pre-existing conditions
“Stable” doesn’t mean “I feel fine today.” Insurers typically apply a 90–180-day stability period before your trip: no new symptoms, no medication changes, no new treatments. Even a small dosage tweak by your doctor can reset the clock. If you manage something like high blood pressure or diabetes, read the 2026 policy wording word by word — and look for pre-existing condition riders (extra-fee add-ons that cover you even without perfect stability). For seniors on Super Visa policies, this rider is often worth every penny.
Winter sports and adventure riders
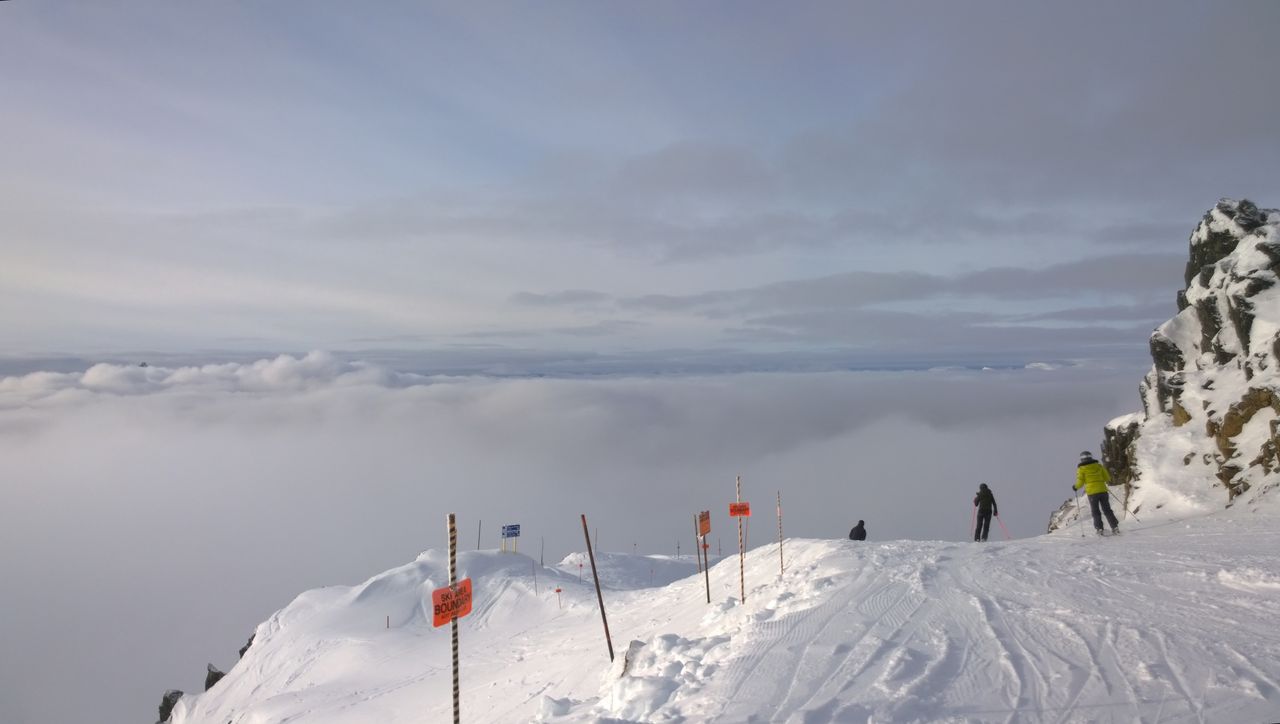
I almost bought a cheap policy without a winter-sports rider the year I planned to ski Whistler — caught it in the fine print at 11 PM the night before my flight. (My spreadsheet has a dedicated column for this now.) The photo above is the dream; the claim is the nightmare. Standard policies often exclude:
- Usually excluded outright: backcountry skiing, heli-skiing, ice climbing.
- Covered with an adventure/winter-sports add-on: resort skiing and snowboarding, mountain biking, zip-lining, shallow scuba.
- Almost never covered: professional sports, skydiving, high-altitude climbing.
Many 2026 adventure packages now bundle search and rescue — if you get lost hiking in the Rockies, the helicopter bill may be covered. Watch the altitude cap: some policies stop at 3,000 metres. See our 3-day Whistler itinerary if the slopes are calling, and budget for the rider.
Alcohol, drugs, and illegal acts
Injuries while under the influence of alcohol or drugs are almost always excluded — and yes, that includes cannabis, even though it’s legal in Canada. Anything that happens while you’re breaking the law (including driving without a valid license) is out too.
Providers, deductibles, and what they cost in 2026
The 2026 market is competitive, with a few names coming up again and again: Manulife and Allianz Global Assistance are the staples (direct billing with most Canadian hospitals, multilingual 24/7 support), TuGo is popular with younger travelers and IEC participants for its flexible sports add-ons and fast digital claims, and World Nomads targets adventurers with broader sports coverage. The “best” provider depends entirely on your age, health, and plans — compare at least three quotes, and compare the wording, not just the price.
The deductible is your biggest lever on price. Most 2026 plans offer $0 to $10,000:
| Deductible | Trade-off |
|---|---|
| $0 | Zero stress at the clinic — but the highest premium. |
| $500 | The sweet spot for most travelers; can cut ~20% off the premium if you’re young and healthy. |
| $2,500+ | Only if you have the cash on hand for minor emergencies. For seniors on Super Visa, a lower deductible is usually the smarter move. |
For a fuller picture of what a Canada trip costs overall, see our tipping guide for tourists and the master Canada travel guide.
How to buy, activate, and file a claim
Buy before you leave home. Policies bought after arrival usually carry a 48-hour to 7-day waiting period for new illnesses — which is exactly when you don’t want a gap. Save your policy number and Summary of Benefits in your phone; most 2026 insurers have apps with a digital ID card to show at the front desk.
The claim process, step by step:
- Call the 24/7 assistance line first if it’s an emergency. They’ll point you to a preferred provider with direct billing — the hospital bills the insurer, not you.
- Get a claim reference number and the claim form.
- Keep every receipt — originals, with the drug name and price on pharmacy receipts. No detailed receipt, no reimbursement.
- Ask the doctor for a medical certificate describing the diagnosis and treatment.
- Submit through the online portal or app, and follow up until it’s confirmed complete.
Two pitfalls that catch people constantly: lost pharmacy receipts (you usually pay for meds upfront and claim back later), and coordination of benefits — if you have credit-card coverage plus a private policy, you must tell both companies. Non-disclosure can delay or kill a claim.
The bottom line? Get covered before you fly, pick the right rider for your plans, and keep your documents where you can reach them at 2 AM in an ER waiting room. You’ve got this.
FAQs about Canada travel insurance
Do I legally need travel insurance to visit Canada in 2026?
Ordinary tourists are not legally required to carry travel insurance, but it is strongly recommended — a single hospital night can cost a non-resident ~$3,500–5,000. Super Visa holders and IEC/Working Holiday participants are legally required to have qualifying coverage, and border officers can ask anyone for proof of financial self-sufficiency.
What are the Super Visa insurance requirements in 2026?
Your policy must provide at least $100,000 CAD in emergency medical coverage, be valid for one full year from the date of each entry, cover health care, hospitalization and repatriation, and come from a Canadian insurer or an OSFI-authorized foreign insurer. It must be paid in full (or with a deposit on an installment plan) — IRCC does not accept quotes as proof.
What kind of insurance do I need for IEC or a Working Holiday?
Private health insurance covering your entire stay, including medical care, hospitalization, and repatriation. If your policy is shorter than your intended stay, the border officer may issue a work permit that expires when your insurance does — and you cannot extend it later. IRCC recommends buying coverage only after you receive your Port of Entry letter.
How much does travel insurance for Canada cost in 2026?
It depends on age, coverage, and deductible. A young healthy traveler can pay a modest premium for a two-week trip with a $500 deductible, while a Super Visa policy ($100,000 coverage, one year) runs roughly ~$1,100–1,800/year for ages 40–54, rising to ~$2,900–4,800 for ages 70–74. Higher deductibles lower premiums; pre-existing-condition riders raise them.
Does travel insurance cover pre-existing conditions?
Only if the condition meets the policy’s “stability” requirements — typically no new symptoms, medication changes, or treatments in the 90–180 days before your trip. Undisclosed conditions are the most common reason claims are denied. Many insurers offer pre-existing-condition riders for an extra fee, which are worth considering for seniors.
Will my policy cover skiing and winter sports?
Not by default. Basic policies often exclude skiing and snowboarding, so you need a winter-sports or adventure add-on — a knee injury on the slopes can cost ~$15,000 for surgery and rehab. Backcountry skiing, heli-skiing, and ice climbing are usually excluded entirely; check the altitude cap (often 3,000 m) and confirm search-and-rescue coverage if you’re heading into the backcountry.
3 comments